Picture someone with $1.8 million saved, a paid-off house, no debt, and a monthly spend the math cleared years ago.
They’re still driving to the office every morning.
Not because they have to. Because they never quite gave themselves permission to stop.
I work with pre-retirees and corporate executives in Minnesota, and I see this constantly. People who are clearly ready on paper, finding reasons. Below are the four signs I run into again and again, along with the ones people keep explaining away.
Sign 1: You hit your number, then quietly moved it
You set a number. Maybe it was $2 million. Maybe $1.5 million. Maybe it was the point where your investment income covered your spending.
At some point in the last couple of years, you got there.
Then you moved the target.
Maybe the market felt uncertain. Maybe you wanted one more bonus cycle. Maybe the number became $2.5 million, or $3 million, or “just until the kids finish school,” which somehow never quite finishes.
This almost never has anything to do with math.
Behavioral finance has a name for what’s driving it. Loss aversion, defined by Nobel laureate Daniel Kahneman and Amos Tversky through their prospect theory research. Their core finding is that your brain processes a potential loss roughly twice as painfully as it processes an equivalent gain.
So when you think about stopping your paycheck, your brain isn’t just calculating a loss of income. It’s amplifying it.
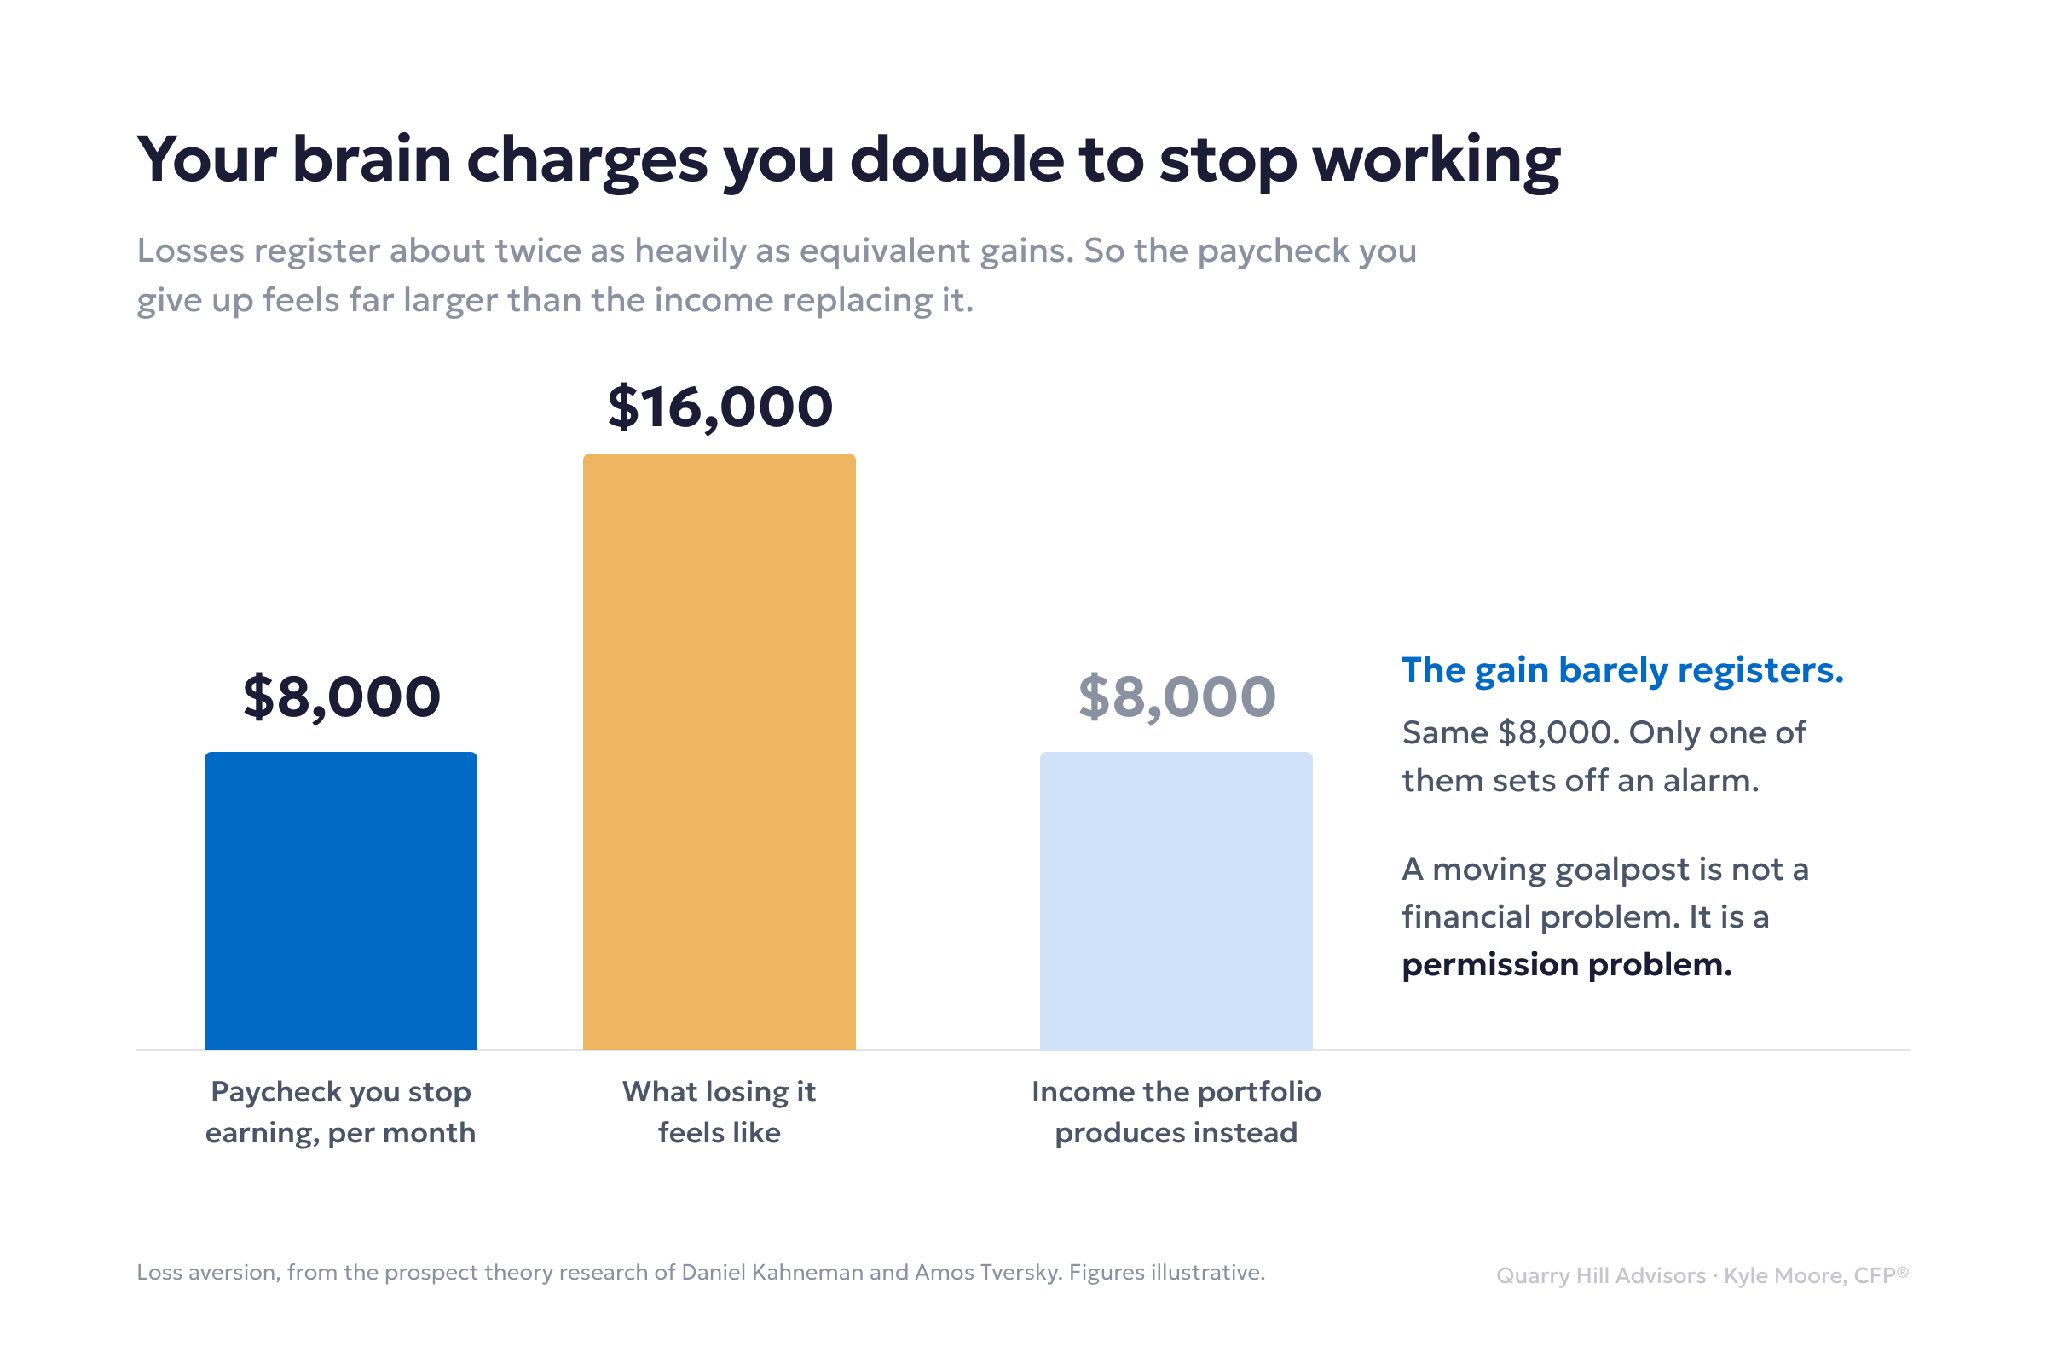
The $8,000 a month you’d stop earning feels emotionally like losing $16,000. The $8,000 your portfolio would generate to replace it barely registers by comparison.
And so you keep moving the target. Not because the math requires it, but because your brain is doing everything it can to avoid setting off that alarm.
Here’s the thing. If you can name that pattern, you can see it for what it is. A moving goalpost is not a financial problem. It’s a permission problem.
You hit the number years ago. The work now is convincing yourself that you did.
Sign 2: You’re stuck in the one more year trap
One more year feels free.
You’re earning good income. You’re adding to the portfolio. You aren’t drawing anything down yet. From the outside it looks like pure upside.
It is not free.
Every additional year you keep working carries an opportunity cost that most people never put a number on, and that cost lives in the tax code.
When you retire, and before Social Security and required minimum distributions kick in, you have what planners call the gap years. It’s a window where your taxable income drops dramatically. In that window you can do Roth conversions, moving money from your pre-tax accounts into a Roth IRA and paying tax on it now at a potentially lower marginal rate than you’ll see for the rest of your life.
While your W-2 is still running, any dollars you try to convert stack on top of your wages. You’re converting at 22%, maybe 24%, and it doesn’t pencil out.
Then you retire. Your taxable income drops to near zero. You’re living off savings.
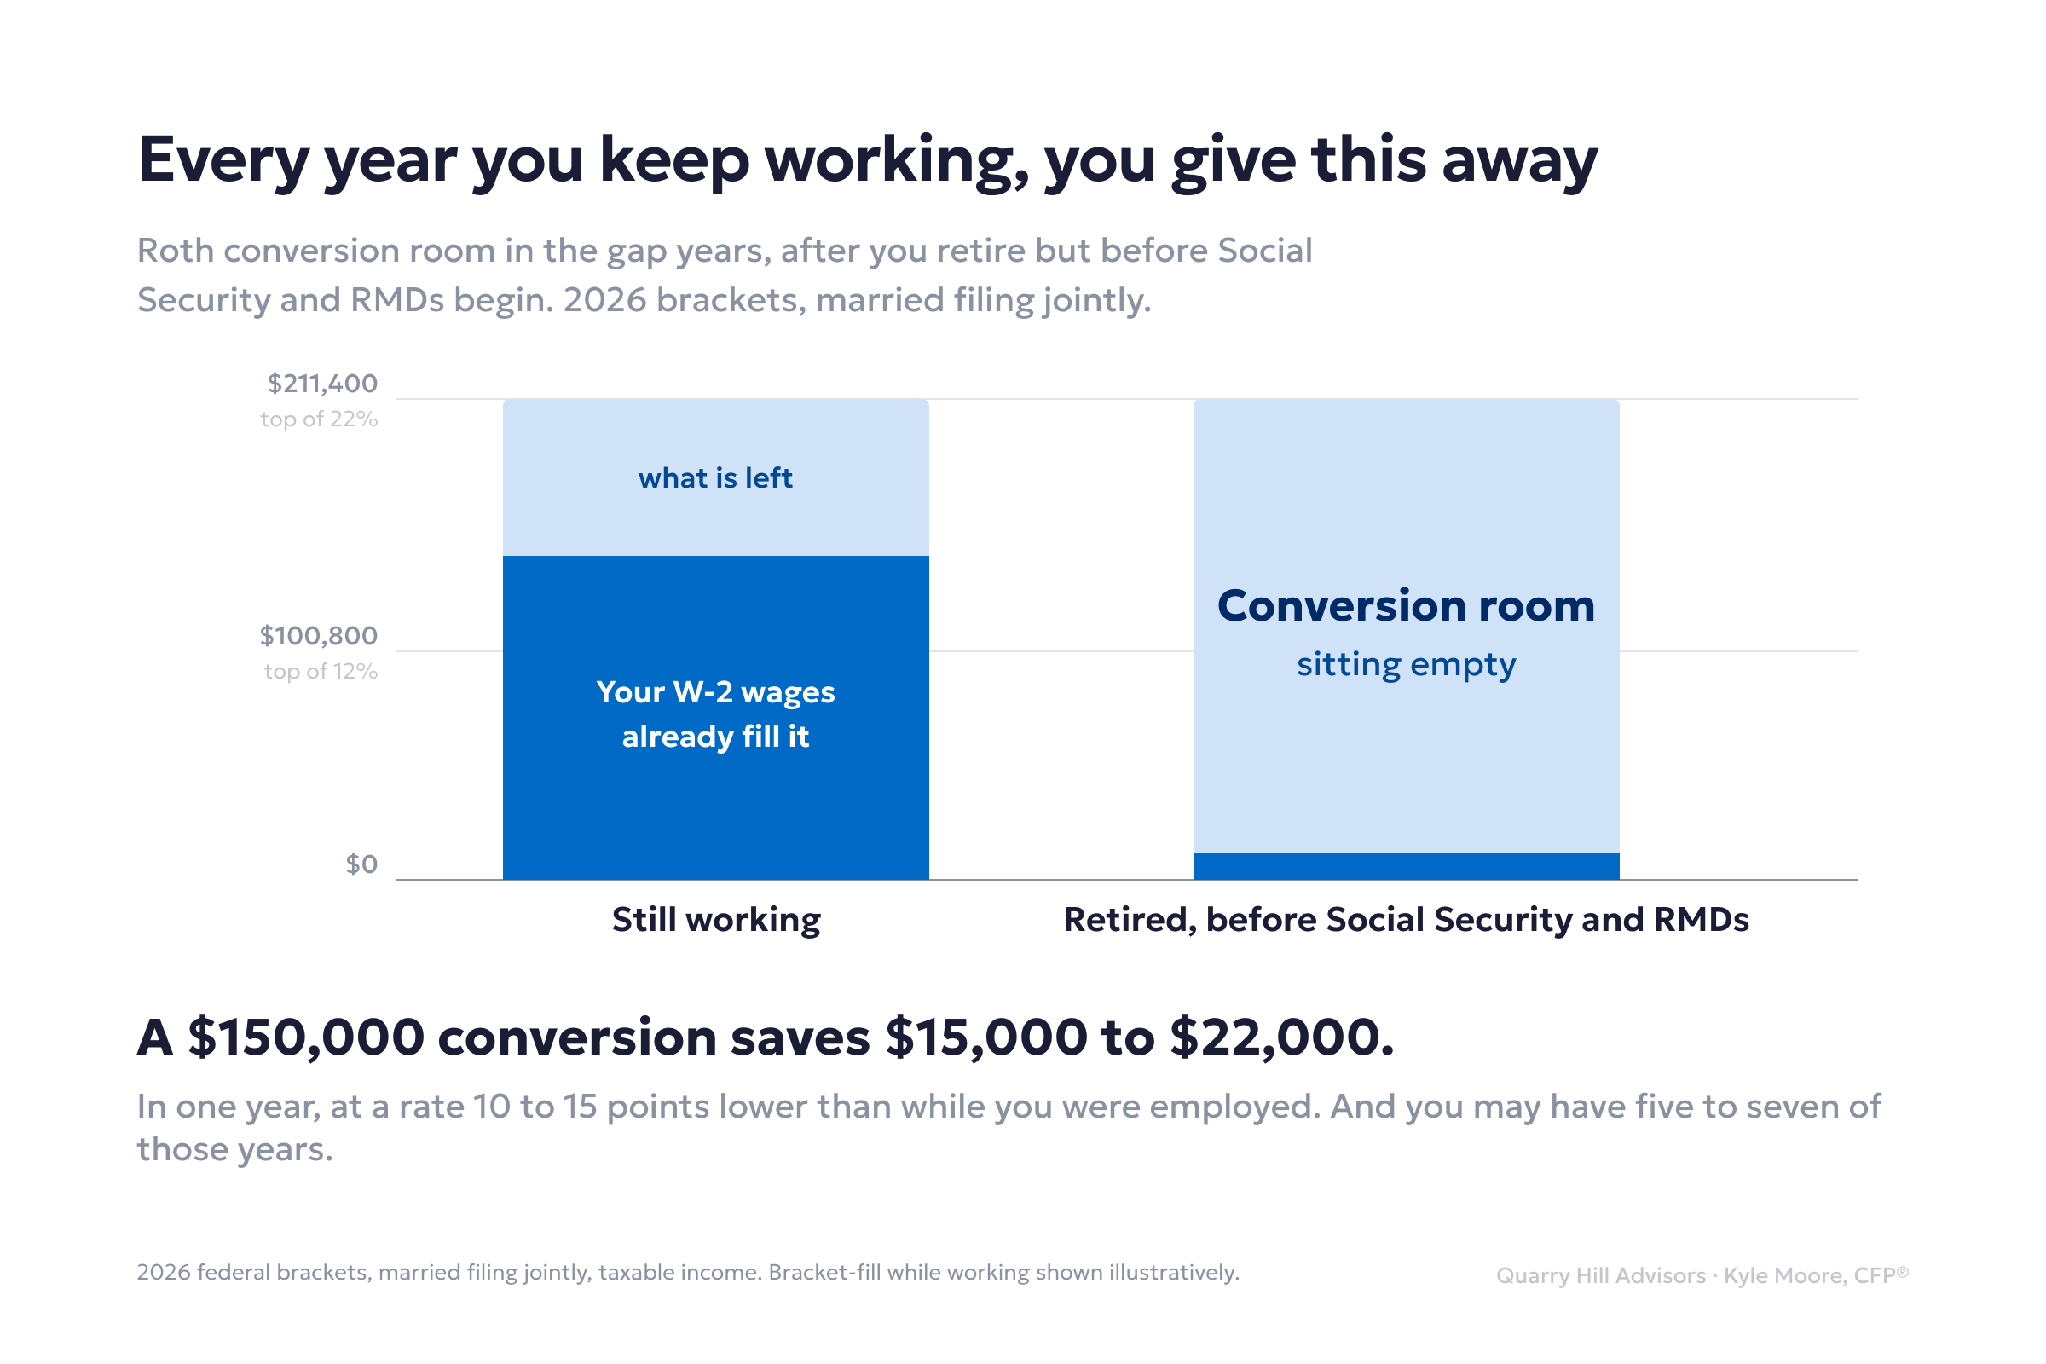
Under the 2026 tax brackets, a married couple filing jointly can fill up the 12% bracket with roughly $100,800 of taxable income, and the 22% bracket up to roughly $211,400. That is an enormous amount of conversion room, and it’s sitting there entirely empty because you’re still working.
The average tax on a conversion in those gap years can run 10 to 15 percentage points lower than what you’d pay while you’re still employed. On a $150,000 conversion, that spread is somewhere between $15,000 and $22,000 in real tax savings. In a single year.
And you might have five or seven of those years before RMDs begin and before Social Security adds income back into the picture.
So when you say “one more year,” what you’re actually saying is that you’ll keep paying full price for your tax bill while giving up the cheapest conversion years you will ever have.
That’s not conservative. That’s expensive.
Sign 3: You only stress test the disaster
This one is interesting to me, because it’s framed so reasonably that people don’t recognize it as a bias.
Ask someone in their early 60s why they aren’t ready to retire and they’ll walk you through a very detailed scenario. The market crashes in year one and they’re down 30% right when they’re starting to pull from it. They know the term: sequence of returns risk. Then inflation runs higher than expected for a decade. Then a significant health event at 68. Then they live to 97 and run out of money at 89.
All of that is worth modeling. We do model it. A margin of safety really does matter.
But when’s the last time you stress tested the good version?
What does the plan look like if the market delivers something close to its historical average over the next 25 years? What does it look like if your spending actually does what retirement research shows it tends to do?
Morningstar researcher David Blanchett’s work, commonly called the retirement spending smile, found that real spending in retirement does not run flat with inflation for 30 years. His analysis of the RAND Health and Retirement Study found that the average retiree follows a U-shaped curve. Spending runs higher in the early active years, drifts lower through the middle decades when people are less mobile, then ticks back up later in life for health care. The median retiree follows more of a smirk, where spending just gradually declines in real terms.
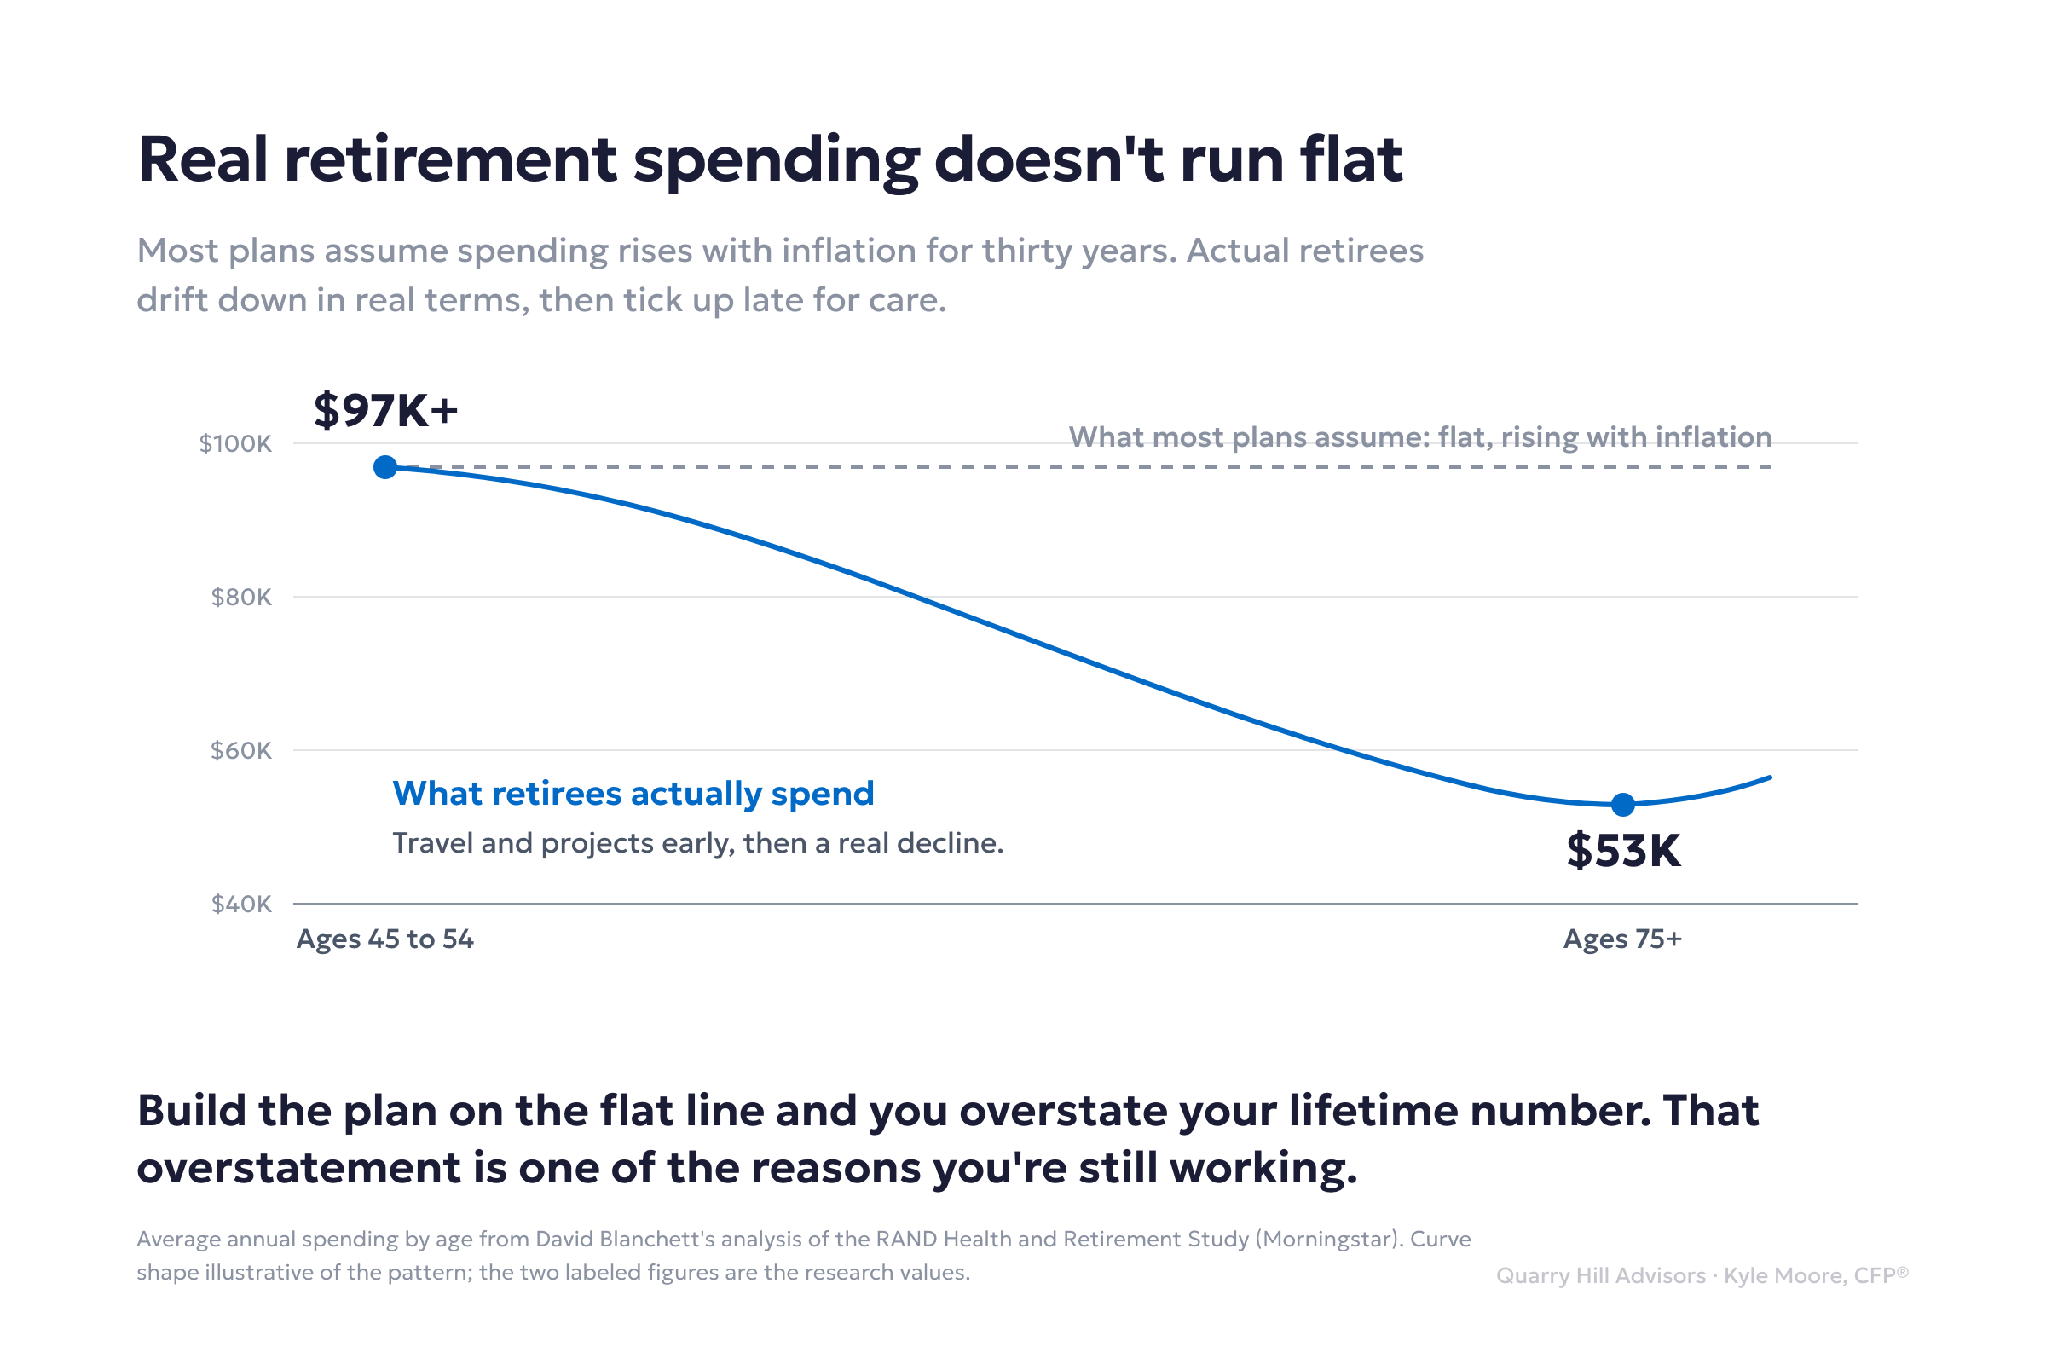
Blanchett also found that people 75 and older spend around $53,000 per year on average, compared to over $97,000 annually for people aged 45 to 54.
Real spending drops materially as you age into retirement, even for people who could afford to spend more.
So if your retirement plan is built on a flat spending assumption rising with inflation every single year for three decades, you have probably overestimated your lifetime number significantly. And that overstated number is one of the reasons you’re still working.
I’m not saying ignore the downside. I’m saying that planning only for catastrophe while ignoring the probable outcome is not conservative planning. It’s fear with a little math attached.
You only get one retirement. The goal is to get the most out of it, not to optimize the ending balance of your estate.
Sign 4: You never modeled what retirement actually costs
Most retirement projections I see from people before we’ve worked together share a common assumption. Spending starts at some monthly number and rises with inflation every year for 30 years.
It’s a clean, simple model. It’s easy to build. For most real retirees it’s completely wrong.
The practical implication that most plans miss entirely is this: the early years of retirement and the late years have very different cost profiles, and the middle decades are almost always cheaper than the flat line model assumes.
In the first decade, most people I work with want to travel, help their adult kids, maybe renovate a property. Real spending in those years tends to run higher than their current household number. Then in their mid-70s, travel slows down, the big projects are finished, and spending naturally drops in real terms. Later in life, if care is needed, it might tick back up.
That actual curve, modeled honestly, produces a lifetime spending total that is often meaningfully lower than the flat line projections.
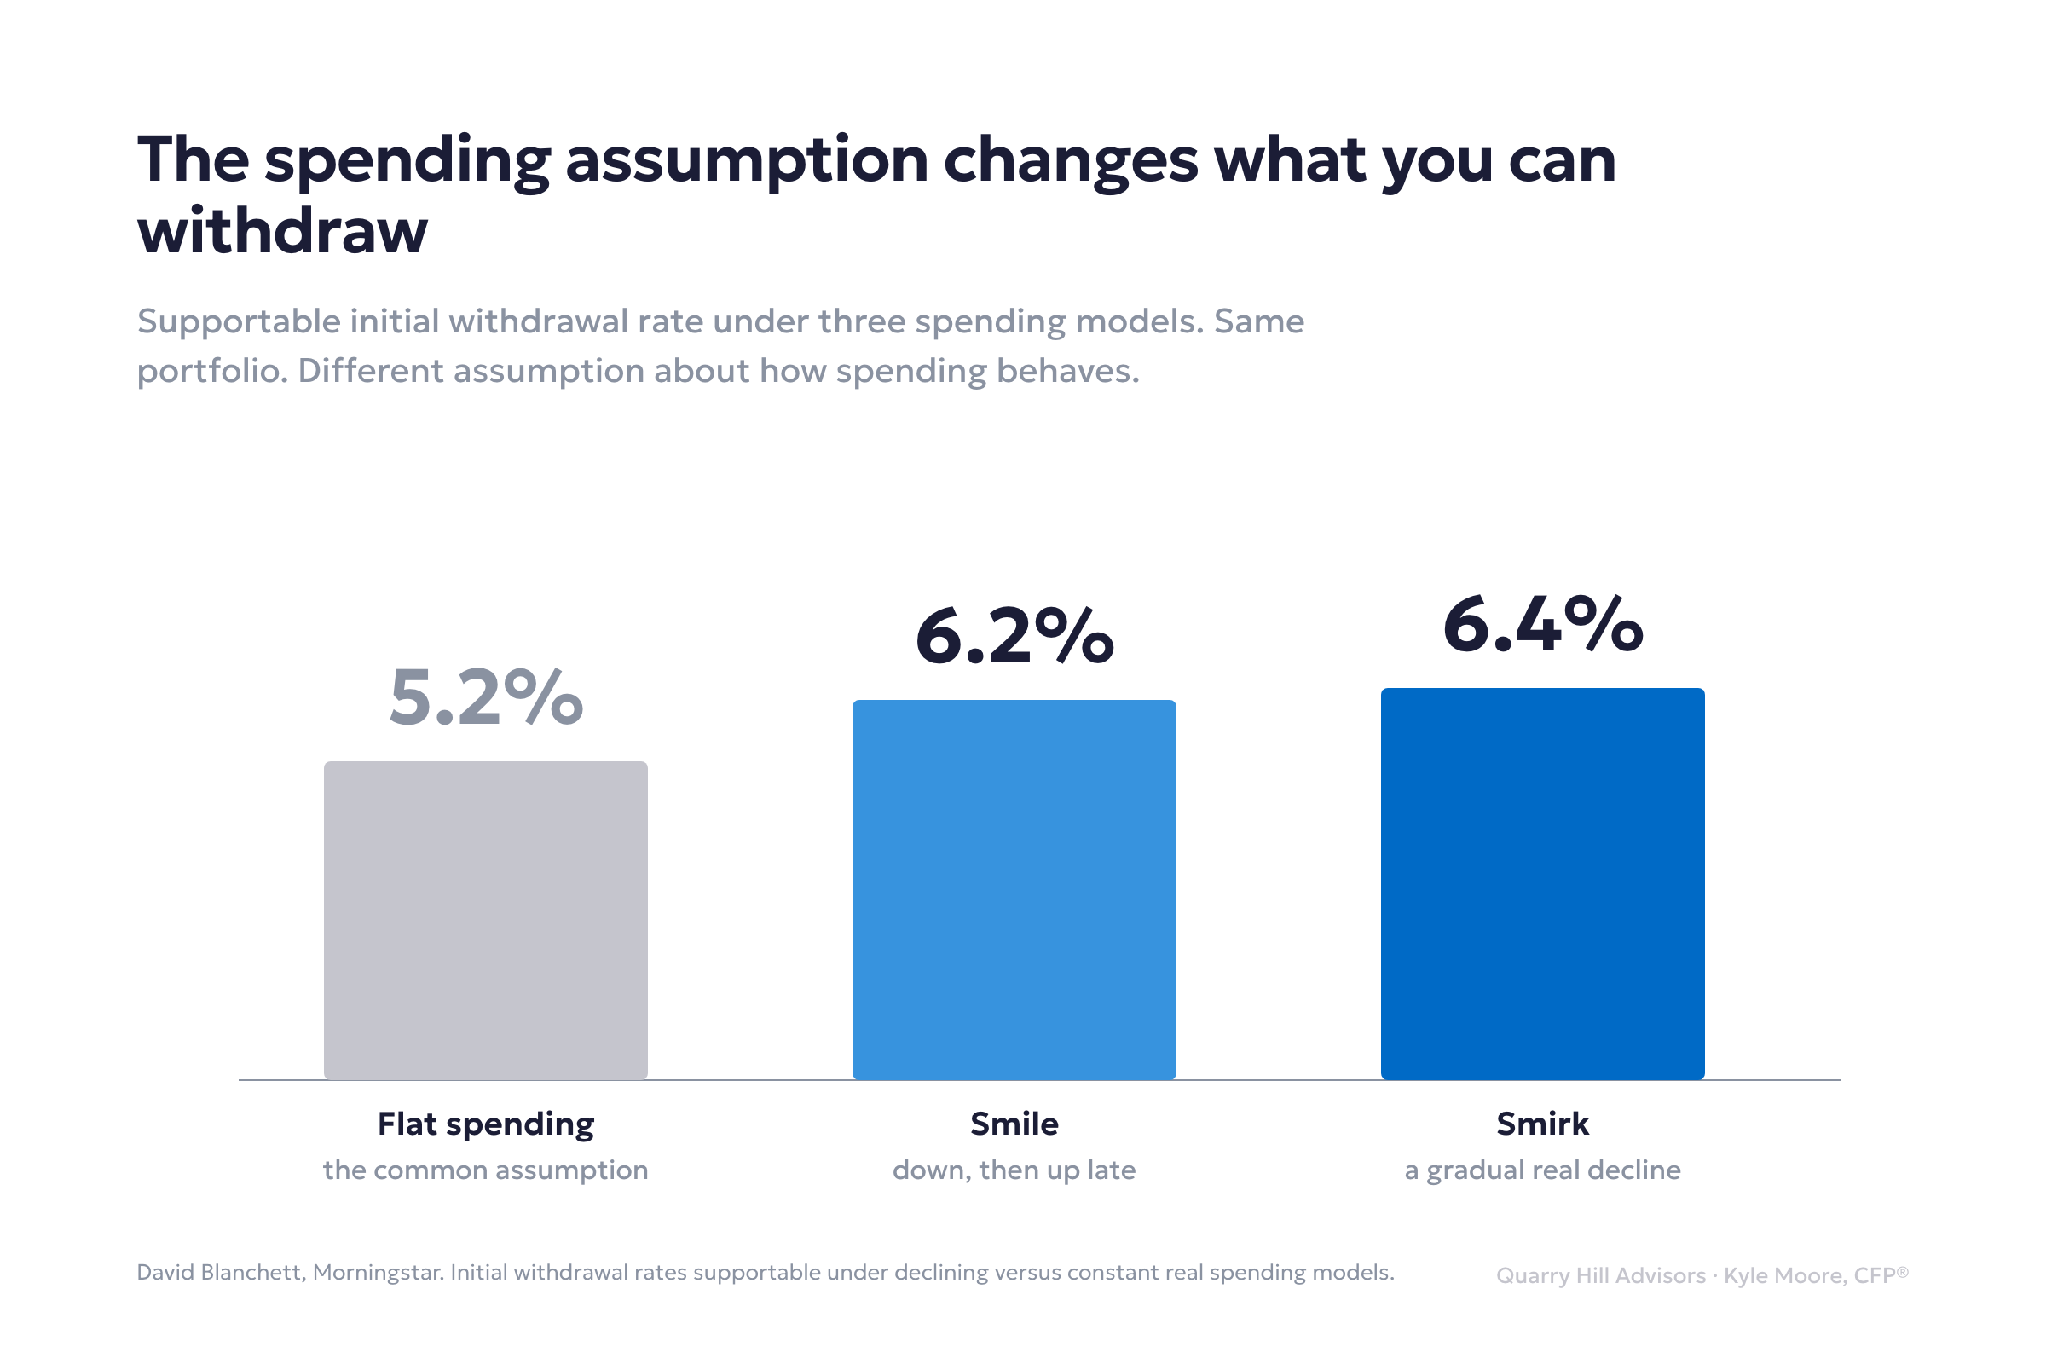
According to Blanchett’s research, advisors who use a declining spending model rather than a constant spending assumption may be able to support initial withdrawal rates of around 6.2% under a smile pattern and 6.4% under a smirk, compared to roughly 5.2% under a flat spending assumption.
That difference in assumed withdrawal rate has real consequences for how long people think they need to keep working.
The flat assumption is not safe. It’s a blunt instrument that overstates the lifetime number and keeps people working years longer than their actual spending patterns would require.
If you have never looked at your retirement spending in buckets, early years against middle years against late years, you haven’t actually modeled what retirement costs for you. You’ve modeled a generic assumption. And that generic assumption may be the reason you keep telling yourself you’re not ready.
The real readiness test: three questions that actually matter
Readiness is not purely a math question, but it is anchored to three very specific, very practical things. If you can answer yes to all three, I’d argue the conversation about whether you’re ready is mostly settled.
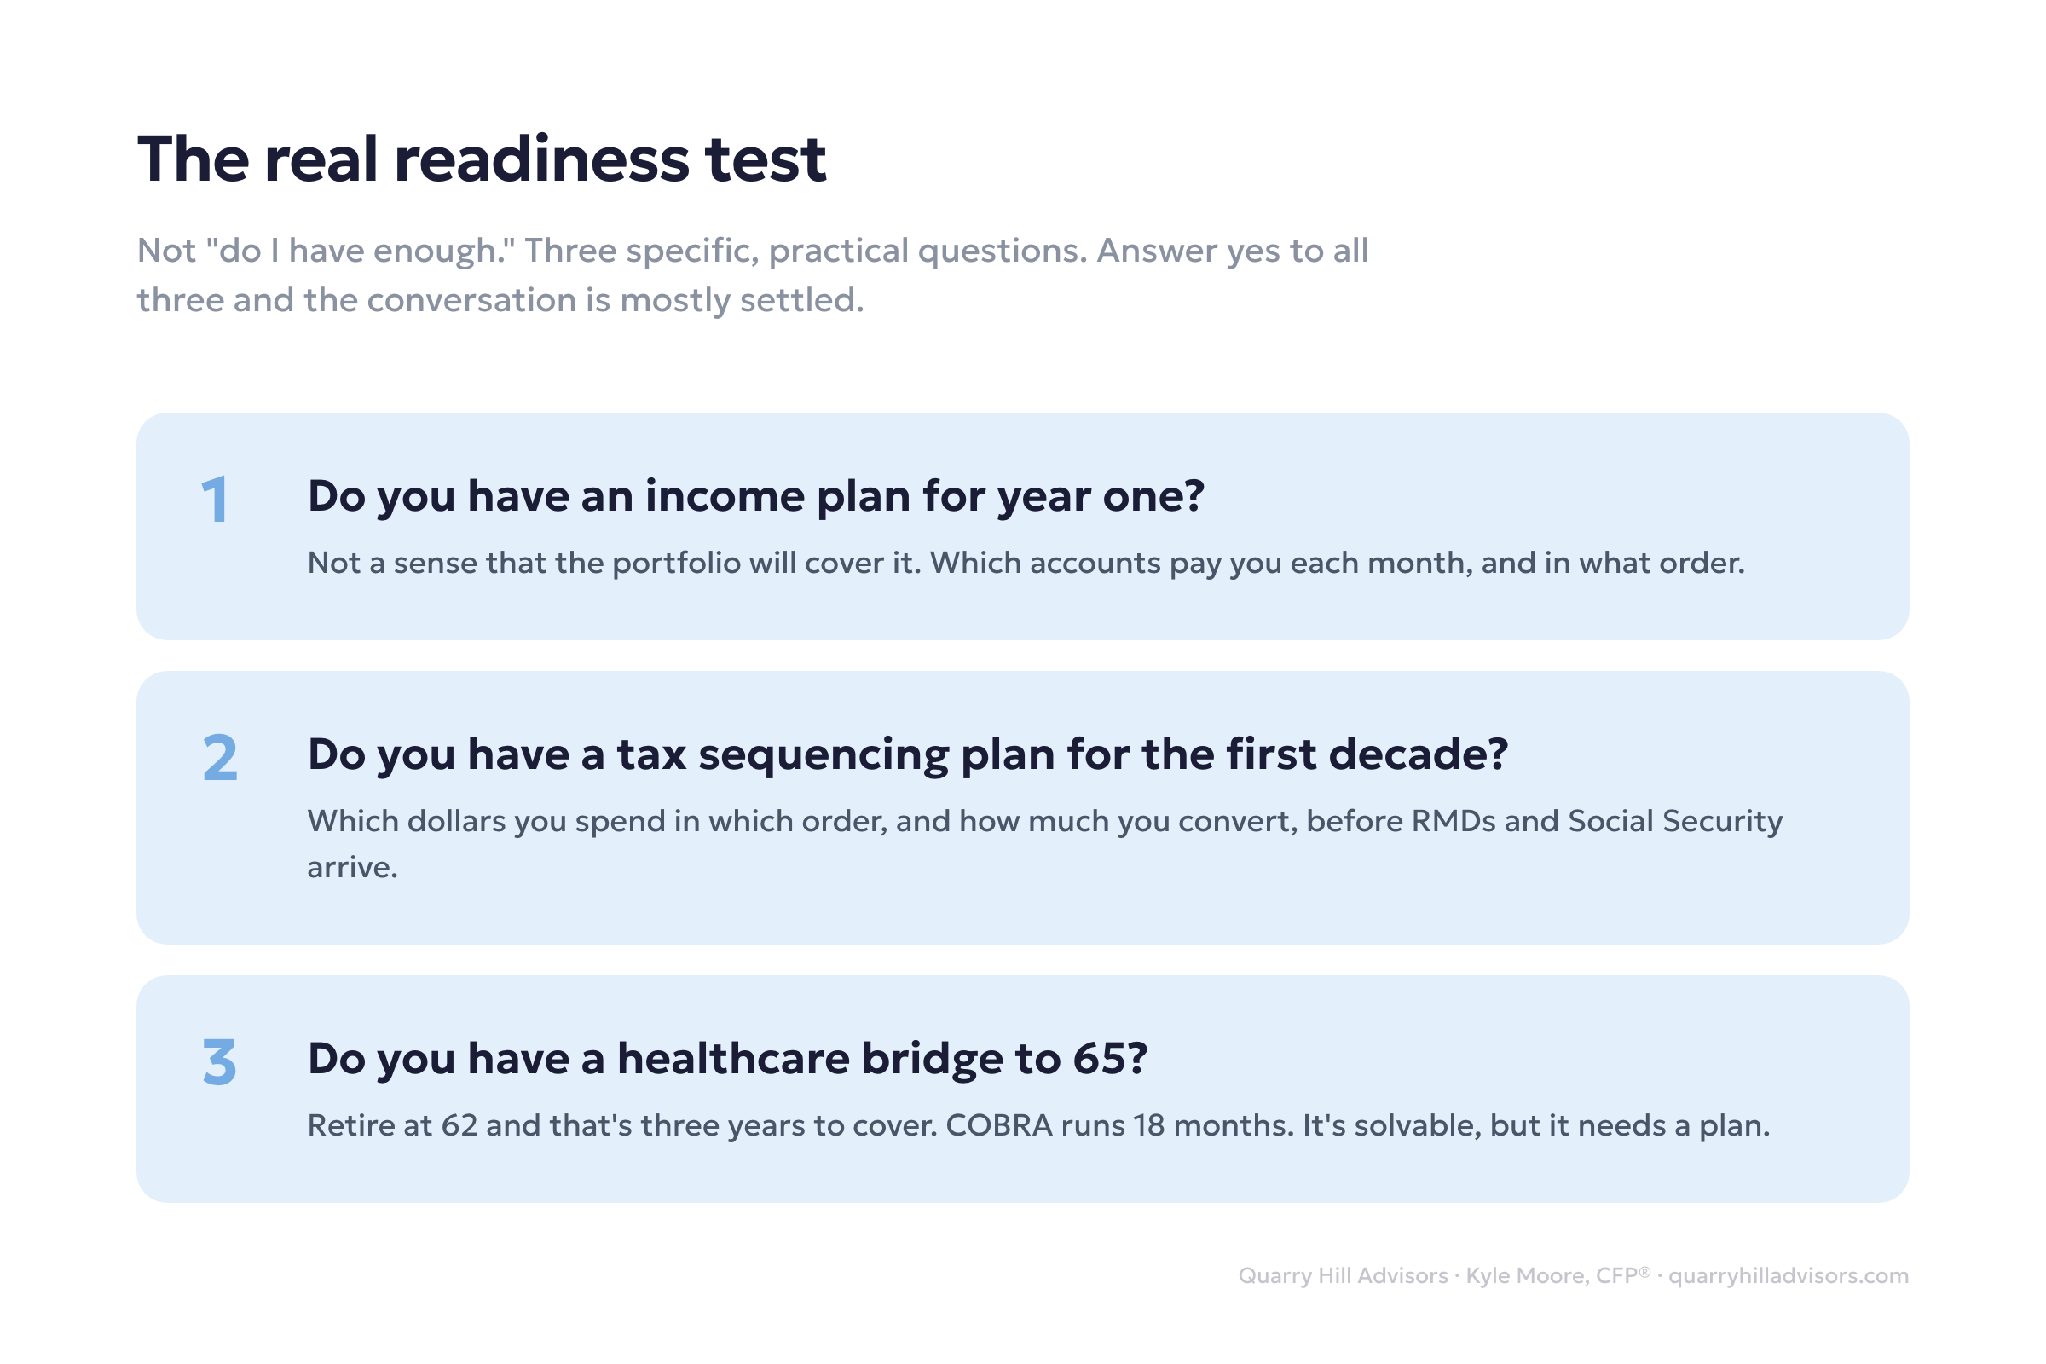
Do you have an income plan for year one?
Not a vague sense that the portfolio will cover it, but a specific answer to the question of where the money comes from each month the first year you stop working. Which accounts do you pull from? What’s the sequence? If you have that answer, you’ve cleared the first bar.
Do you have a tax sequencing plan for the first decade?
This is the Roth conversion question, the account ordering question, the question of which dollars you spend in which order to manage your brackets over the years before required minimum distributions and Social Security kick in. Per the IRS 2026 tax tables, married couples filing jointly can fill up the 22% bracket at roughly $211,400 of taxable income. If your gap-year income is well below that, you have conversion room you aren’t using. Every year you delay retirement, you give that room away.
Do you have a healthcare plan for the bridge before Medicare at 65?
This is where I see people who have done everything else right get blindsided. If you retire at 62, you have three years of coverage to figure out. COBRA runs 18 months. ACA marketplace plans are available and can be structured intelligently based on your income in those years. It is solvable, but it requires a plan, not just an intention to figure it out.
If you can answer yes to all three of those, the question is not whether you’re ready. The question is whether you’re willing to accept that certainty does not exist in retirement, and it never did. Waiting for it is just a more expensive version of that same fear.
One more number worth sitting with
The Federal Reserve’s Survey of Consumer Finances shows that the median retirement savings for households aged 55 to 64 is $185,000.
So if you’re sitting on $1.5 million or $2 million and a paid-off house, you are not in the same conversation as the median American. You’re in a conversation with yourself about permission, and that’s worth taking seriously.
I’ve been doing this long enough to know how the families who come to us and say “we probably waited a year or two longer than we needed to” actually say it. There’s a quiet regret in it that has nothing to do with money. They’re talking about time, the one resource that does not compound for you.
You don’t get a do-over on this.
The math may have cleared. The work now is letting yourself believe it.
Let’s look at your numbers
If you recognized yourself anywhere in this, the next step is an honest plan that answers those three readiness questions for your specific situation. That’s the work we do at Quarry Hill Advisors.
Schedule a discovery meeting and let’s look at what the numbers actually say for you.
Kyle Moore, CFP®, is a fee-only financial planner and the founder of Quarry Hill Advisors in Minnesota. He specializes in helping high-earning professionals and retirees navigate the financial decisions surrounding the transition to retirement.
This material is intended for educational purposes only. You should always consult a financial, tax, or legal professional familiar with your unique circumstances before making any financial decisions. Nothing contained in the material constitutes a recommendation for purchase or sale of any security, investment advisory services or tax advice. The information and opinions expressed in the linked articles are from third parties, and while they are deemed reliable, we cannot guarantee their accuracy.